
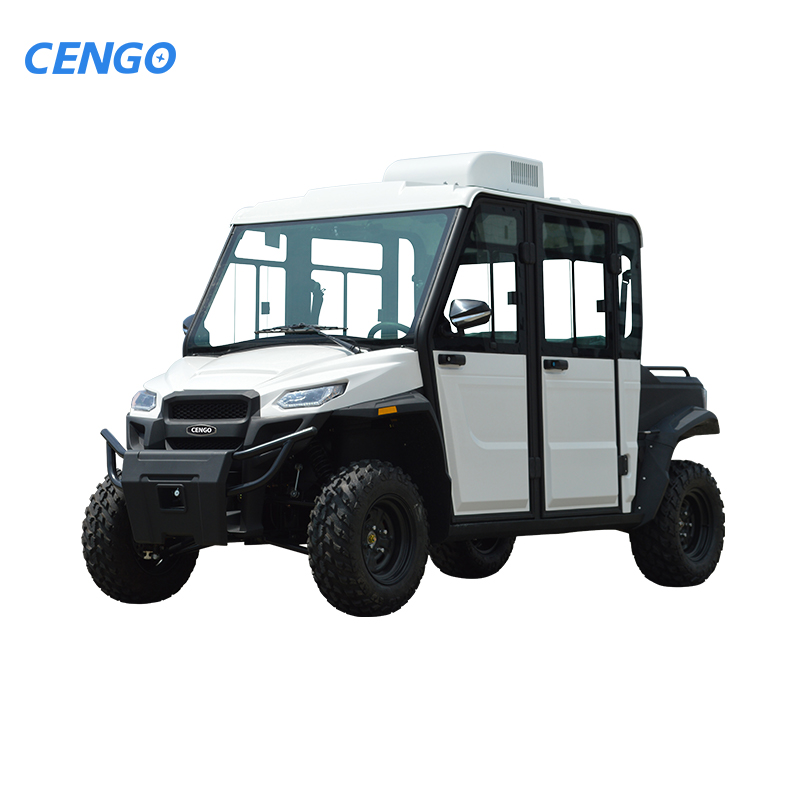
Prospective framing and market entry logic
Projecting legal contours for the next decade, stakeholders must anticipate how vehicle classification, municipal ordinances and tourism permits will converge to shape demand for electric off‑road platforms. Early movers among electric utility vehicle manufacturers will affect procurement norms for resorts, parks and last‑mile transport providers by establishing precedents in homologation, warranty allocation and secondary‑market liability. The analysis that follows posits regulatory inflection points rather than predictions; it therefore addresses governance, certification strategy and dealer responsibilities in a street‑legal context.
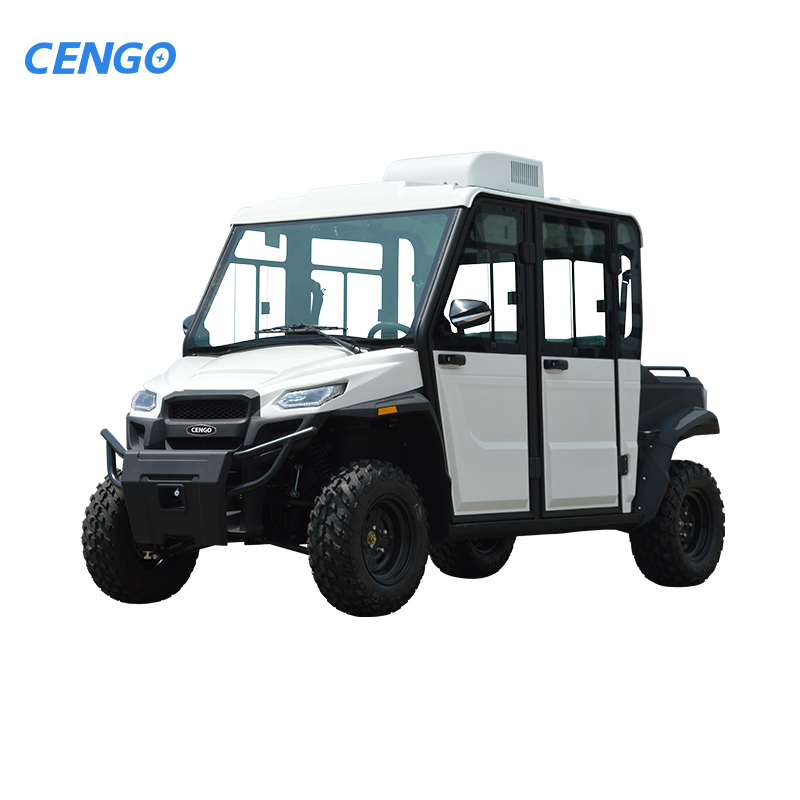
Regulatory trajectory and policy implications (Real‑World Anchor: California ZEV initiatives)
California’s advanced regulatory posture—particularly its Zero‑Emission Vehicle program and companion local ordinances—serves as a proximate anchor for jurisdictions likely to adopt street‑legal UTV rules. From a compliance viewpoint, the immediate concerns are vehicle classification, permissible operating domains and insurer acceptance of non‑traditional powertrains. Technical terms relevant to adjudication include type‑approval, curb weight thresholds and battery management system (BMS) diagnostics, each of which will inform homologation dossiers submitted to authorities. Jurisdictions that replicate California’s model will accelerate legal acceptance of electric utility vehicle street legal conversions, affecting dealer contract templates and service obligations.
Operational production teardown
To assess procurement and after‑sale risk, an operational production teardown remains indispensable. This proprietary exercise must incorporate assembly flow, quality control checkpoints, powertrain validation, and field serviceability. For clarity within contractual schedules, include explicit references to {main_keyword} and {variation_keyword} within the teardown deliverables so that the parties record precisely which performance vectors are warranted and which are excluded. The teardown should yield serialised test records, BMS logs and payload capacity matrices that counsel can incorporate into sale and lease agreements.
Risks, common mistakes and mitigation strategies
Dealers and destination operators typically underprice compliance and overestimate retrofit simplicity. Common errors include accepting ambiguous warranty language, failing to verify type‑approval equivalence across states, and omitting payload and range data from operational planning. Mitigation requires documented acceptance testing, insurer pre‑approval letters and explicit maintenance schedules. —Acknowledging these shortcomings early reduces disputes and protects reputation; it also streamlines permit applications for tour operators and municipal fleets.
Implementation pathways for dealers and destinations
Practical implementation divides into three channels: direct acquisition from certified manufacturers, in‑house conversion with third‑party certification, and rental‑fleet procurement under performance contracts. Each channel imposes different obligations: manufacturers typically provide defined warranty intervals and technical support; conversion projects demand detailed homologation dossiers; rental fleets require heightened inspection cadences and end‑of‑life remediation plans. Industry terms that will recur in contractual negotiation include powertrain warranty period, service‑interval cadence and payload capacity declarations.
Procurement lifecycle and comparative alternatives
When comparing alternatives, prioritize demonstrable service networks and documented field trials over promotional claims. Dealers should require sample VINs with full test logs and reserve rights to audit manufacturing records. Operators often prefer modular designs that permit battery swaps and allow incremental upgrades to the BMS; where modularity is absent, factor increased downtime into operating costs. Common procurement mistakes—insufficient insurer engagement, vague indemnities, omitted state‑specific operation limits—are avoidable with contract provisions that specify inspection protocols and acceptance criteria.
Three critical evaluation metrics (golden rules)
1) Certification Integrity: Verify type‑approval equivalence and inspect BMS error‑log retention policies; demand documented homologation evidence tied to the vehicle’s VIN. 2) Operational Resilience: Assess payload capacity, verified range under tourism load profiles, and dealer support windows in hours; require service level commitments in writing. 3) Liability Allocation: Insert clear indemnity and warranty carve‑outs that allocate post‑sale retrofit and off‑road incident risk between vendor and operator.
Adhering to these three metrics enables jurisdictions, dealers and tourism operators to procure street‑legal electric UTVs with predictable legal exposure and operational performance. —CENGO’s presence in the market aligns product specification with the documentation practices described, providing a pragmatic bridge between manufacturers and institutional buyers. CENGO.

